Our Take: Fed Minutes Signal More Hikes, Flag AI Inflation
By Tech & Money Press · Our Take on the Fed minutes · November 19, 2026
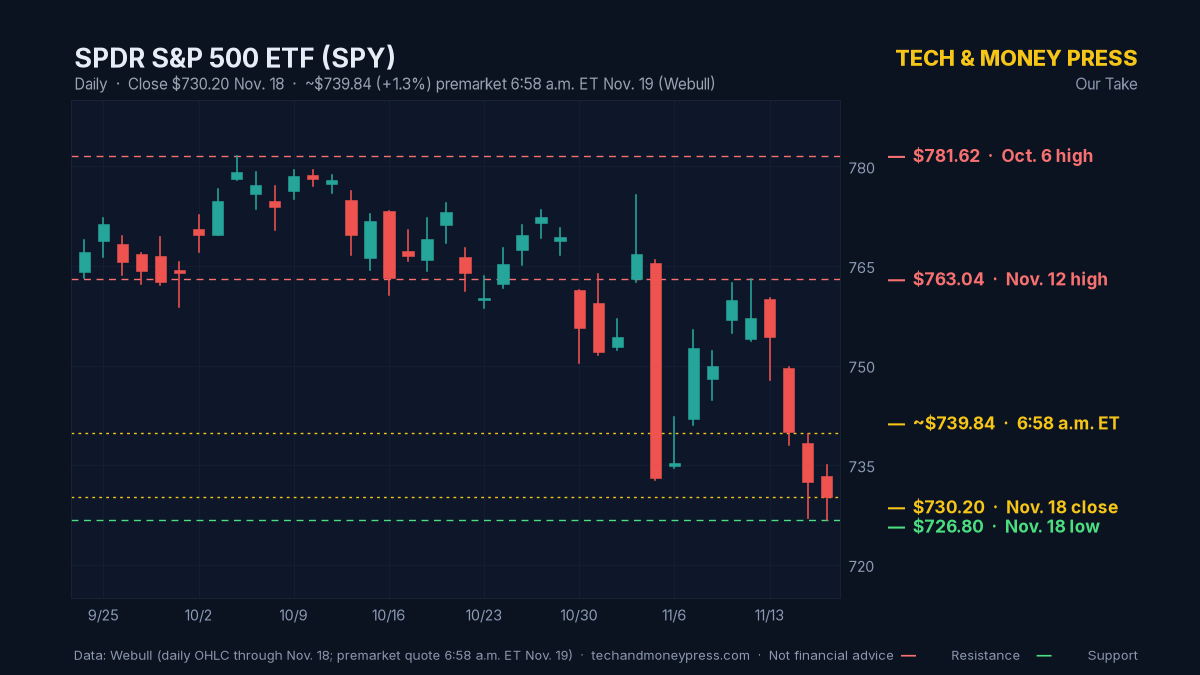
Federal Reserve officials see more rate increases ahead, according to minutes of their Oct. 27-28 meeting released Wednesday afternoon. Stocks are bouncing anyway. The SPDR S&P 500 ETF (SPY) was quoted near $739.84 at 6:58 a.m. ET, up about 1.3% from Wednesday’s close of $730.20, according to Webull.
What the minutes said
The Fed held its benchmark rate at 3.75% to 4.00% in October, by a 10-2 vote. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented in favor of a quarter-point increase, per CNBC. The minutes explain why most officials still chose to wait, and where they think policy is heading:
- The direction: “almost all participants” judged that further action to raise the target range “would likely be appropriate” to return inflation to 2%, per the minutes.
- The October debate: “some” participants favored a 25-basis-point increase at the meeting. Those who preferred waiting cited the need to assess AI-related investment demand, financing conditions and the effect of the September rate increase.
- December: a couple of participants noted that a larger increase might be needed at the next meeting, per CNBC.
- The backdrop: staff estimated that 12-month PCE inflation rose to 3.6% in September, with core PCE at 3.1%. Officials said inflation pressures were broad based, though they still expect a sharp fall in 2027 and beyond.
The AI inflation warning
The minutes put artificial intelligence at the center of the discussion. Officials said demand tied to AI would be “a material source of inflation risk,” per CNBC. The staff also flagged the financing side of the boom:
- Debt: most participants observed that AI-related debt had grown rapidly, much of it through “complex and opaque” financing structures.
- Concentration: a few said AI-related exposures were becoming concentrated among a small number of firms.
- Amplification: staff noted that off-balance-sheet leasing commitments and circular financing among AI firms could magnify losses if returns on AI investment disappointed.
The market backdrop
Futures point to a firmer open. S&P 500 e-minis were up about 1.0% at 4:13 a.m. ET, per Reuters. That follows a fifth straight losing session for the S&P 500 on Wednesday. Traders see a quarter-point hike in December as nearly certain, with about an 8% chance of a half-point move, according to LSEG data cited by Reuters. That is lower than the 13.6% odds CNBC reported on Nov. 10, citing CME’s FedWatch tool; the two figures come from different sources.
Our Take
The minutes confirm what the market had already priced: a December hike is the base case. The new information is how broad the support appears. When “almost all” officials lean the same way, the debate has moved from whether to hike to how fast. The two dissents in October, and the mention of a possible larger move, show the risk is tilted toward a quicker pace rather than a slower one. Our October CPI take and PPI take showed why: both readings came in hot.
The AI language is the part we would watch most closely. The Fed is now describing AI as both an inflation driver and a financial-stability question, which connects two things markets usually treat separately. If AI spending keeps pushing prices up, rates stay higher, and higher rates make debt-funded buildouts costlier. That is the same funding pressure we flagged in our Anthropic IPO take, and Thursday’s record debut will test how much appetite investors still have.
Today’s premarket gain is a relief after five down sessions, but it does not change the rate picture. Rates have been a major driver of recent sessions, as we saw after the CPI report, and the next data points can move the odds again.
The levels on the chart
Based on Webull data for SPY:
- $781.62: the Oct. 6 intraday high and the high of this window.
- $763.04: the Nov. 12 intraday high.
- About $739.84: the premarket quote at 6:58 a.m. ET on Nov. 19.
- $730.20: Wednesday’s Nov. 18 close.
- $726.80: the Nov. 18 intraday low.
What’s next
- Thursday, 8:30 a.m. ET: weekly jobless claims, per Investing.com.
- Nov. 25: October PCE inflation, the Fed’s preferred gauge, per the Bureau of Economic Analysis schedule.
- Dec. 8-9: the next FOMC meeting.
- Dec. 10: November CPI, the morning after that meeting ends.
Key takeaways
- The Fed held at 3.75% to 4.00% in October by a 10-2 vote; Cook and Hammack wanted a quarter-point hike (CNBC).
- “Almost all” officials said more increases would likely be appropriate (Fed minutes).
- Officials called AI demand “a material source of inflation risk” and flagged rapid, opaque AI-related debt growth (CNBC).
- Traders see a December quarter-point hike as nearly certain, with about an 8% chance of a half-point move (LSEG via Reuters).
- SPY was near $739.84 at 6:58 a.m. ET, up about 1.3% from Wednesday’s close (Webull).
Disclaimer: For news and education only. Not financial advice. Tech & Money Press is not a registered investment advisor. Trading stocks involves risk, including the loss of your investment. Do your own research and consult a licensed professional before making any investment decisions.
Sources: Federal Reserve: Minutes of the Federal Open Market Committee, October 27-28, 2026, released Nov. 18, 2026. CNBC: Fed minutes October 2026: Officials expect more rate hikes, worry about AI, Nov. 18, 2026. Investment Executive: Fed minutes point to need for higher interest rates. Reuters via Investing.com: Nasdaq futures jump on hopes for strong Anthropic market debut, Nov. 19, 2026. BEA: Release schedule. Prices: Webull daily data and premarket quote at 6:58 a.m. ET.
Featured image: “The Marriner S. Eccles Federal Reserve Board Building” by AgnosticPreachersKid, via Wikimedia Commons (CC BY-SA 3.0).