Our Take: CoreWeave Earnings Beat Buys Time, Not a Free Pass
By Tech & Money Press · Our Take on CoreWeave’s third-quarter results · November 11, 2026
CoreWeave gave the AI trade the report it needed. The AI cloud provider said Tuesday after the bell that third-quarter revenue rose 168% from a year earlier to $3.66 billion, ahead of the $3.55 billion analysts expected, according to LSEG data cited by CNBC and Reuters. It raised its full-year revenue forecast, lifted its profit outlook by more than a quarter and said its revenue backlog grew to about $132.5 billion.
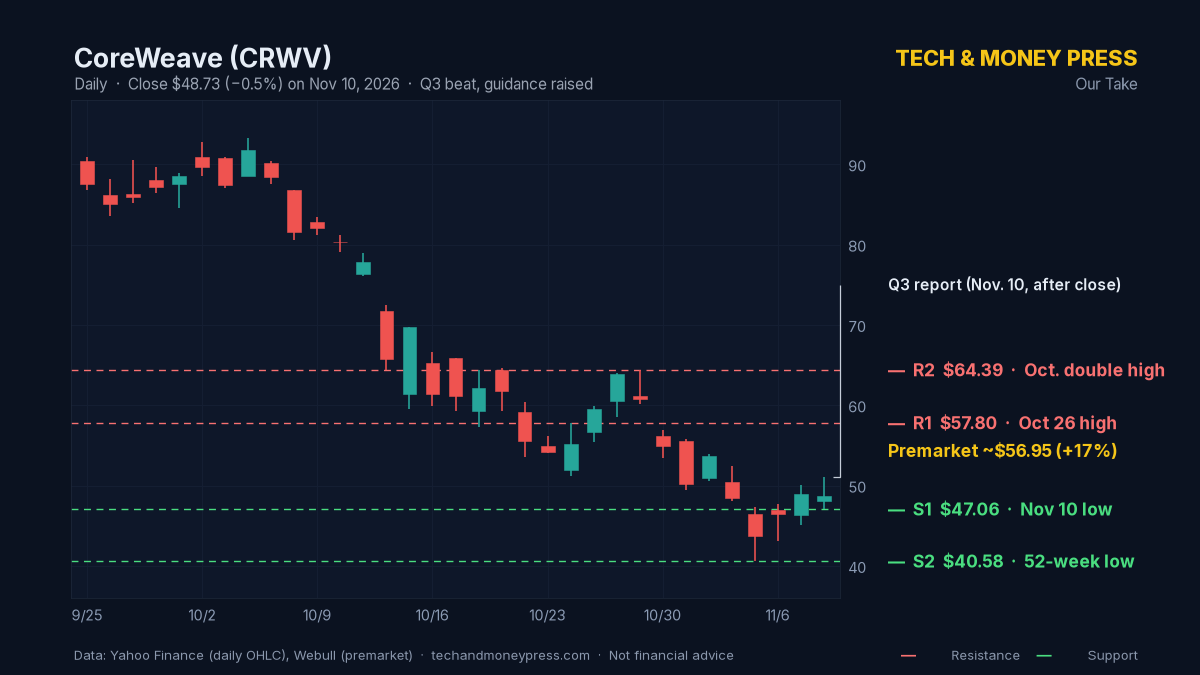
The stock responded. CoreWeave (CRWV) closed Tuesday at $48.73 and was trading around $56.95 in premarket action as of 7:24 a.m. ET Wednesday, up about 17%, according to Webull data. The rebound helped lift Nasdaq 100 futures about 1.7% early Wednesday, Reuters reported.
But the report also put the company’s biggest problem in plain numbers. In the third quarter, CoreWeave paid more in net interest than it earned in operating income, by roughly four times. Demand is not CoreWeave’s issue. Paying for the build-out is.
What CoreWeave reported
The headline numbers were strong across the board:
- Revenue: $3.661 billion, up from $1.365 billion a year earlier. CEO Michael Intrator said revenue rose by more than $1 billion from the second quarter.
- Adjusted loss per share: 95 cents, better than the $1.16 loss analysts expected (LSEG). On a GAAP basis, CoreWeave lost $709 million, or $1.27 a share, compared with a $110 million loss a year earlier.
- Adjusted EBITDA: $2.256 billion, a 62% margin.
- Adjusted operating income: $379 million, roughly a 10% margin. CoreWeave said it reached double-digit adjusted operating margins a quarter ahead of plan.
- Revenue backlog: about $132.5 billion as of Sept. 30, up from $104 billion at the end of June.
The guidance was the bigger story. CoreWeave now expects 2026 revenue of $13.0 billion to $13.3 billion, up from $12.4 billion to $13.2 billion. Analysts polled by LSEG had been at $12.86 billion. Adjusted operating income guidance rose to $1.275 billion to $1.375 billion from $960 million to $1.15 billion, a 26% increase at the midpoint. Analysts surveyed by Visible Alpha had expected $1.07 billion, according to CNBC.
The company also raised its annualized run-rate revenue target to $20 billion to $21 billion by the end of 2026 and said it still expects more than 1.85 gigawatts of active power at year-end. Reuters reported the company is largely sold out of capacity through next year and sees about ten times as much demand as it has capacity.
The part the stock pop skips
Here is the other side of the ledger. Net interest expense was $846 million in the third quarter, up from $310 million a year earlier. Operating income was $207 million. For the fourth quarter, CoreWeave guided interest expense to $1.05 billion to $1.15 billion.
Spending is going up too. CoreWeave now expects 2026 capital expenditures of $37 billion to $39 billion, raising the low end of its prior $35 billion to $39 billion range because it plans to deliver infrastructure to customers sooner. Quarterly capital spending reached $14.5 billion, up from $9.4 billion in the second quarter, according to Reuters.
Management’s answer is that the customers are paying for much of it. Intrator pointed to financing backed by customer contracts, operating cash flow and “approximately $9 billion in customer prepayments and deposits expected in the next three months alone.” Reuters reported the company now says it will be profitable on an adjusted basis in the first half of 2028.
That is the trade-off in one sentence: a $132.5 billion backlog on one side, and a long, expensive road to turn it into profit on the other.
Our Take
This was the right report at the right time. Over the past month, neocloud stocks have traded like a referendum on whether the AI build-out can pay for itself. We covered that pressure going into the print in CoreWeave confronts ‘doom cycle’ narrative as neocloud credit risk overshadows growth, and the market has been charging companies like CoreWeave more for credit, as we noted in The AI credit card is getting costlier. Tuesday’s numbers answer the demand question decisively. A backlog that grew by about $28.5 billion in a single quarter, with guidance raised above Wall Street’s forecast, is not what a collapsing business looks like.
What the report does not do is change the funding math. CoreWeave’s interest bill is rising faster than its operating profit, and fourth-quarter interest expense could top $1 billion. That makes CoreWeave a rate-sensitive stock as much as an AI stock. That matters right now. As we wrote in our October CPI take, the 2-year Treasury yield jumped 17 basis points to 4.73% on Tuesday after a hot inflation report, and traders have fully priced in a December rate hike. Higher-for-longer rates hit companies that borrow to build harder than most.
So we read the 17% premarket jump as a relief rally, not a re-rating. Even at about $56.95, the stock would still be roughly 60% below its 52-week high of $138.25. The market is giving CoreWeave credit for demand, but it isn’t yet giving credit for profits that are still more than a year away.
The levels we are watching
CoreWeave fell from around $90 in early October to a 52-week low of $40.58 on Nov. 5 before stabilizing. The premarket move takes the stock straight toward resistance:
- Resistance 1: $57.80, the Oct. 26 high. A daily close above it would be the first sign the earnings gap can hold.
- Resistance 2: $64.39, the matching highs of Oct. 20 and Oct. 29. That is where the last two rebound attempts failed.
- Support 1: $47.06, Tuesday’s low. A close back below it would mean the earnings gap has been fully erased.
- Support 2: $40.58, the Nov. 5 low and the 52-week low.
Premarket prices can change a lot by the 9:30 a.m. ET open. A gap is not a confirmed breakout until the stock closes above resistance. Wednesday is Veterans Day: the stock market is open with normal hours, but the U.S. bond market is closed, so there is no Treasury-yield read on the move today.
Key takeaways
- CoreWeave’s third-quarter revenue rose 168% to $3.66 billion, beating the $3.55 billion estimate. The adjusted loss of 95 cents a share beat the $1.16 forecast.
- 2026 revenue guidance rose to $13.0 billion to $13.3 billion, and adjusted operating income guidance rose 26% at the midpoint. Backlog reached about $132.5 billion.
- Net interest expense of $846 million was about four times operating income of $207 million, and Q4 interest expense is guided to $1.05 billion to $1.15 billion.
- 2026 capex is now $37 billion to $39 billion. CoreWeave targets adjusted profitability in the first half of 2028.
- The stock was up about 17% premarket at around $56.95. A close above $57.80 would confirm the move. A close below $47.06 would undo it.
Disclaimer: This article is for informational and educational purposes only and is not financial advice. Tech & Money Press is not a registered investment advisor. Trading stocks involves risk, including the loss of your investment. Do your own research and consult a licensed professional before making any investment decisions.
Sources: CoreWeave Reports Strong Third Quarter 2026 Results, CoreWeave investor relations, Nov. 10, 2026. CNBC: CoreWeave (CRWV) Q3 earnings report 2026 (LSEG and Visible Alpha estimates). Reuters via Investing.com: CoreWeave targets 2028 profitability as AI demand surges. Reuters via U.S. News: S&P 500, Nasdaq futures rise after CoreWeave soothes AI spending fears. CRWV daily prices: Yahoo Finance, cross-checked with Webull. Premarket price: Webull, 7:24 a.m. ET, Nov. 11, 2026. 2-year Treasury yield: Tech & Money Press, Nov. 10 Our Take.