Our Take: Hot October CPI Puts a December Fed Hike in Play
By Tech & Money Press · Our Take on the October inflation report · November 10, 2026
Consumer prices rose more than expected in October, and traders responded by fully pricing in a Federal Reserve rate hike for December. The Consumer Price Index increased 0.4% last month after a 0.6% jump in September, the Bureau of Labor Statistics said Tuesday. Economists had looked for 0.3%. Core prices, which strip out food and energy, rose 0.3% for a third straight month, versus the 0.2% forecast.
That core reading is the one that matters. Hours before the release, Fed Governor Christopher Waller said that if core CPI came in around 0.3% or higher, “a 50 basis point hike in the policy rate should be considered” at the December 8-9 meeting. The number hit his mark. Stocks gave back part of Monday’s rally, but the sharper move was in bonds: the 2-year Treasury yield jumped 17 basis points to 4.73%, its biggest one-day rise since April 2025.
What the report showed
Headline inflation cooled from September, but not by as much as Wall Street wanted, and the details were not reassuring.
Shelter rose 0.3% and accounted for more than 30% of the monthly increase, according to the BLS. Food jumped 0.5% after being unchanged in September, with groceries up 0.4% and restaurant prices up 0.5%. Energy rose 0.7%, a much slower pace than September’s 5.2% surge, though gasoline still increased 1.0% and electricity 0.9%. Natural gas fell 0.8%.
Under the hood of the core index, transportation services rose 0.8%, recreation 0.8%, motor vehicle insurance 0.7% and medical care 0.3%. Used cars and trucks were one of the few breaks, falling 1.2%.
The BLS did not publish a 12-month inflation rate for most categories. It could not collect prices in October 2025 during last year’s government shutdown, so it has no year-ago comparison for the headline or core indexes. One of the few annual figures it could report: gasoline is up 37.4% from a year earlier.
Why it matters for the Fed
The timing is as important as the number. The Fed’s next meeting is December 8-9. The November CPI report is not due until December 10, the morning after that meeting ends. October’s print is the last CPI policymakers will see before they vote.
Waller, speaking in London at a Bank of England watchers conference, had already said he was “leaning toward” a quarter-point increase in December even if inflation improved. He supported the Fed’s decision to hold rates at the October meeting, arguing that what matters is following through on hikes the market already expects. But he also drew a clear line: if core CPI stayed around 0.3%, considering only 25 basis points “would put our credibility at risk, a risk I am not eager to take.”
Dallas Fed President Lorie Logan, speaking later on Tuesday, said the October CPI “was higher than expected” and that she is concerned the Fed’s preferred inflation gauge, the PCE price index, could rise when the October reading arrives in a couple of weeks. Logan said the committee needs “at least two more 25-basis-point rate increases,” and that “it may be possible to move more rapidly this winter.”
After the report, traders fully priced in a quarter-point hike at the December meeting and put the odds of a half-point move at 13.6%, according to CNBC, citing CME Group’s FedWatch tool. Before the data, the chance of a 50-basis-point hike had been near zero.
How the market reacted
The stock market bent but did not break. SPY closed at $749.92, down 0.4%. QQQ fell 0.7% to $674.76, and IWM dropped 0.7% to $280.58. The S&P 500 finished at 7,520.93, the Dow at 52,231.89 and the Nasdaq Composite at 25,065.87. Nvidia fell about 5.5% and, by one count, accounted for the entire decline in SPY, with gains in other sectors offsetting the rest of the weakness. Technology was the worst-performing group; financials were the best, and six of the 11 S&P sectors finished higher.
Bonds told a more hawkish story. The 2-year yield, which tracks Fed policy expectations most closely, rose 17 basis points to 4.73%. The 10-year yield rose about 10 basis points and settled near 4.99%. The 30-year yield rose 9 basis points to 5.35%. The iShares 20+ Year Treasury Bond ETF (TLT) fell 1.3%.
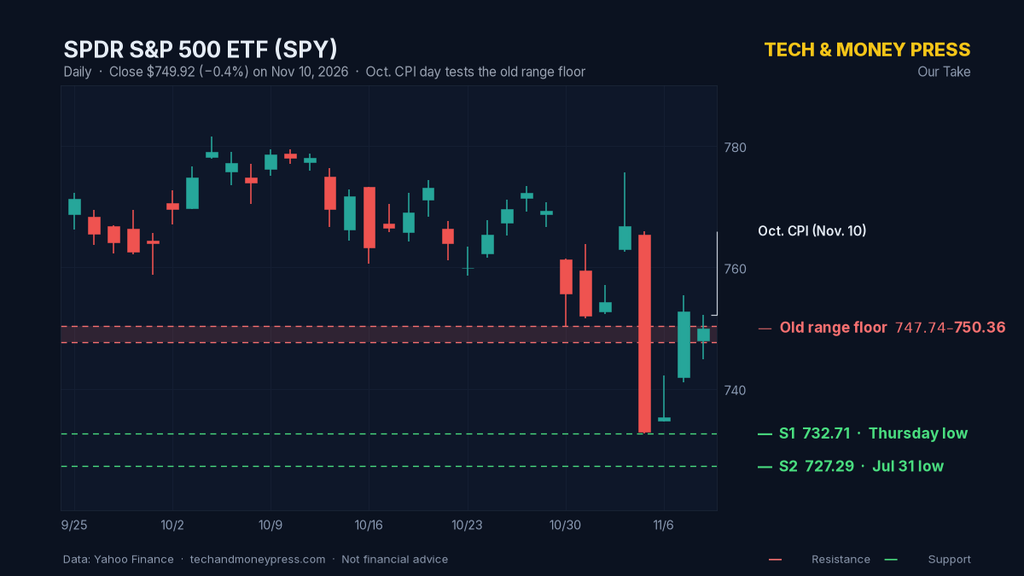
SPY opened at $747.94, slipped to $744.86 and rebounded to close at $749.92, just under Monday’s $752.69 close. In our SPY weekly analysis, we said bulls needed to win back the old range floor at $747.74–$750.36 to argue that last week’s breakdown was a shakeout. Tuesday’s close landed right in that zone. The low of the day undercut it; the close held it.
Wednesday is Veterans Day: the stock market is open with normal hours, but the bond market is closed, so volume could be lighter than usual. That is the setup we flagged in our Stocks to Watch for Wednesday, Nov. 11.
Our Take
This report does not reopen the debate about whether the Fed hikes in December. It closes it. A 25-basis-point move is now the base case, and Waller put a 50-basis-point hike on the table in advance, then got the exact core number he said would justify considering it. Logan, independently, is already talking about two more quarter-point increases and a faster pace this winter. The Fed does not have another CPI print before it has to vote. That combination is why the 2-year yield had its biggest day in a year and a half.
The stock market’s calm should not be mistaken for a clean bill of health. Monday’s 2.4% bounce in SPY did a lot of the work; Tuesday was a digestion session, not a dismissal of the data. We have seen this pattern before. In mid-October, when inflation and rates were the story, software and chip stocks fell together, and individual names followed the indexes rather than their own news. That playbook still applies. When the 2-year yield is moving this fast, tech and other long-duration trades will take their cue from rates, not from earnings headlines.
We are not treating Tuesday’s hold of the $747.74–$750.36 zone as a confirmed reclaim. SPY tagged the area and closed inside it, but only after briefly losing it, and the close is still below Monday’s $752.69. A daily close back above $752.69 would be the first sign that buyers are comfortable living above the old floor. A close back under $747.74, especially if the 2-year yield stays elevated, would put last week’s breakdown back in play, with $732.71 and then $727.29 as the levels underneath.
The next test is not tomorrow’s holiday session. It is whether stocks can hold this zone while the market fully prices a December hike and starts to debate a larger one. Until yields settle, we would rather wait for confirmed closes than guess.
Key takeaways
- October CPI rose 0.4%, above the 0.3% forecast. Core CPI rose 0.3% for a third month, above the 0.2% forecast.
- That core figure met the threshold Waller set hours earlier for considering a 50-basis-point hike on December 8-9. Traders fully priced a 25-basis-point increase and put the odds of a half-point move at 13.6%.
- The Fed will not see November CPI until December 10, after that meeting. October is the last CPI print before the decision.
- The 2-year yield jumped 17 basis points to 4.73%, the biggest one-day rise since April 2025. SPY fell only 0.4% and closed in the $747.74–$750.36 zone we have been watching.
- Shelter, food and services kept core inflation sticky. Energy cooled from September but was still up. Used cars were a rare offset.
Disclaimer: This article is for informational and educational purposes only and is not financial advice. Tech & Money Press is not a registered investment advisor. Trading stocks and bonds involves risk, including the loss of your investment. Do your own research and consult a licensed professional before making any investment decisions.
Sources: U.S. Bureau of Labor Statistics, Consumer Price Index — October 2026. Speech by Fed Governor Christopher J. Waller, November 10, 2026. Remarks by Dallas Fed President Lorie K. Logan, November 10, 2026. FedWatch odds via CNBC, citing CME Group’s FedWatch tool. Index closes via Sharecast and the Associated Press. SPY, QQQ and IWM closes as published in our November 10 watchlist recap (Webull data). Treasury yield and sector details via November 10 market reports.